Deciphering the Exposure Draft of ESRS-40a, the Disclosure Standard for Non-EU Companies: Limitations on Impact and Value Chain Voluntary Standards (Public Comment Period Ends October 31)


Vice Chair of the Global Sustainability Standards Board (GSSB)
Member of the GHG Protocol Expert Working Group (TWG)
Director of Zeroboard Research Institute Tomoo Machiba
September 1, 2026
On July 23, 2026, the European Financial Reporting Advisory Group (EFRAG) published an exposure draft of the sustainability reporting standard "ESRS-40a" for companies outside the EU (hereinafter, ESRS-40a ED) *1) , and is conducting a public consultation (public comment) until October 31 *2) . Our company recently hosted a webinar featuring Mari Kataoka, co-author of the "ESRS Handbook" (Chuo Keizai-sha) and director of the General Incorporated Association "Harmony between Shareholders, Company, and Society," to explain the overview of ESRS-40a, the revised ESRS (European Sustainability Reporting Standard) with its finalized disclosure items, and the "voluntary standards" for companies with fewer than 1,000 employees in the value chain. This article explains the latest information surrounding ESRS and practical points for Japanese companies to address, based on the Contents of the webinar.
 Mari Kataoka and the author during a conversation at our company's webinar (August 25, 2026)
Revised ESRS finalized – approximately 90% of items covered, disclosure items reduced by 61%.
ESRS-40a is a standard developed based on ESRS, which is the implementation standard for EU companies under the Corporate Sustainability Reporting Directive (CSRD). In February 2025, the European Commission proposed the "Omnibus I," outlining measures to reduce the reporting burden on European companies to maintain their competitiveness. In response, EFRAG proceeded with the consideration of a simplified version and submitted a final draft to the European Commission in December 2025. On July 3, 2026, the European Commission adopted the "Revised ESRS" (renamed from Simplified ESRS) as delegated regulation C(2026)5010. Following approval by the European Parliament and the European Council, it will be officially issued in the latter half of the same year *3) (Figure 1).
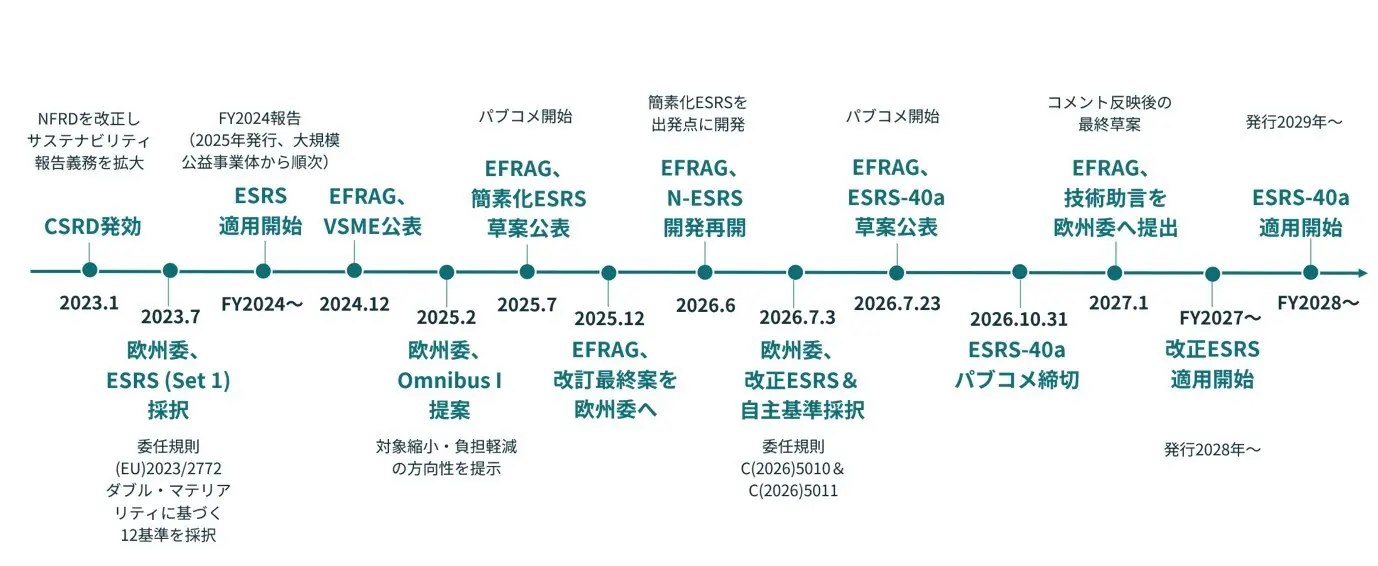 Figure 1: Timeline surrounding the ESRS revision <br />Zero board Create
The key points of the finalized Contents include a significant increase in the threshold for applicable companies. For EU companies, the threshold is limited to those with "more than 1,000 employees and net sales exceeding €450 million," halving the number of applicable companies compared to the previous Non-Financial Disclosures Directive (NFRD) and reducing the number by approximately 90% compared to the initial CSRD target. Disclosure requirements (data points) have been reduced to only mandatory items, a 61% reduction from before. The principle of double materiality (evaluating materiality from both impact and financial perspectives) is maintained. Third-party assurance is based on "limited assurance," and the provision for transitioning to "reasonable assurance" in the future has been removed. The changes will take effect from the 2027 fiscal year report (issued in 2028) *3) .
What is ESRS-40a? – An extraterritorial standard based on "fair competition conditions"
ESRS-40a is a standard for companies outside the EU (third countries) based on Article 40a of the Accounting Directive. Initially called N-ESRS (Non-EU ESRS), it was renamed ESRS-40a upon the publication of the draft, after the relevant article. EFRAG cites two objectives for ESRS: to ensure a "level playing field" among companies operating in the EU market, and to ensure transparency regarding the impact that non-EU companies conducting significant business activity within the EU have on people and the environment *1) . In a webinar discussion, Mr. Kataoka stated, "The aim of CSRD is to secure the private sector efforts and funding necessary to achieve Europe's climate change measures and sustainability goals, and ESRS is positioned as a foundation for providing comparable information that will support Financial Institution and others in investing with confidence. It is only natural that companies with a certain level of business activity within the EU should submit evidence of this, just like companies within the EU."
Although ESRS-40a was developed using the revised ESRS as a starting point, there are significant differences. The biggest change is that the basis of reporting has been narrowed to "impact only." The revised ESRS requires reporting based on double materiality, including an item called "RORD," which adds resilience and dependence to financial risks and opportunities. However, in ESRS-40a, the provisions regarding RORD have been removed in principle, and the assessment and disclosure of financial materiality are no longer required. However, it should be noted that providing financial information as contextual information to understand the impact is not strictly excluded. Mr. Kataoka pointed out concerns that reporting based solely on ESRS-40a may be insufficient for investors and other users, stating, "For example, if a company has a significant impact on a local community through water pumping or discharge, and related financial risk information such as the possibility of compensation for damages is omitted, it may not be useful for investment decisions."
The applicable companies are third-country companies with EU subsidiaries or branches whose net sales within the EU (group level, consolidated basis) have exceeded €450 million for the past two consecutive periods, and whose net sales in the previous period exceeded €200 million. EFRAG estimates that the number of companies subject to the changes will be narrowed from approximately 10,000 before the changes to approximately 1,200 after the changes, of which 350-450 are expected to be in the US, 150-200 in the UK, and 100-150 in Switzerland and Japan, etc. *4) In the case of Japanese companies, assuming a typical case where the Japanese subsidiary is the ultimate parent company and is not listed on the EU market, it is important to note that they may be subject to either or both of the following: group-level reporting in third countries and reporting for EU subsidiaries individually (applying the revised ESRS). On the other hand, if the parent company chooses the revised ESRS, it will be exempt from the obligation to report for EU subsidiaries individually (this exemption cannot be used with ESRS-40a alone) (Figure 2). As an exception, if the parent company meets the definition of a "financial holding Company" under the accounting directive, and the subsidiary's business model and operations are independent of each other, there is a provision that exempts the subsidiary or branch from reporting. This will apply to fiscal years beginning on or after January 1, 2028, and the first report should be issued in 2029.
Figure 2: Flowchart for determining applicability of the revised ESRS/ESRS-40a for Japanese companies
(Assuming the Japanese subsidiary is the ultimate parent company)
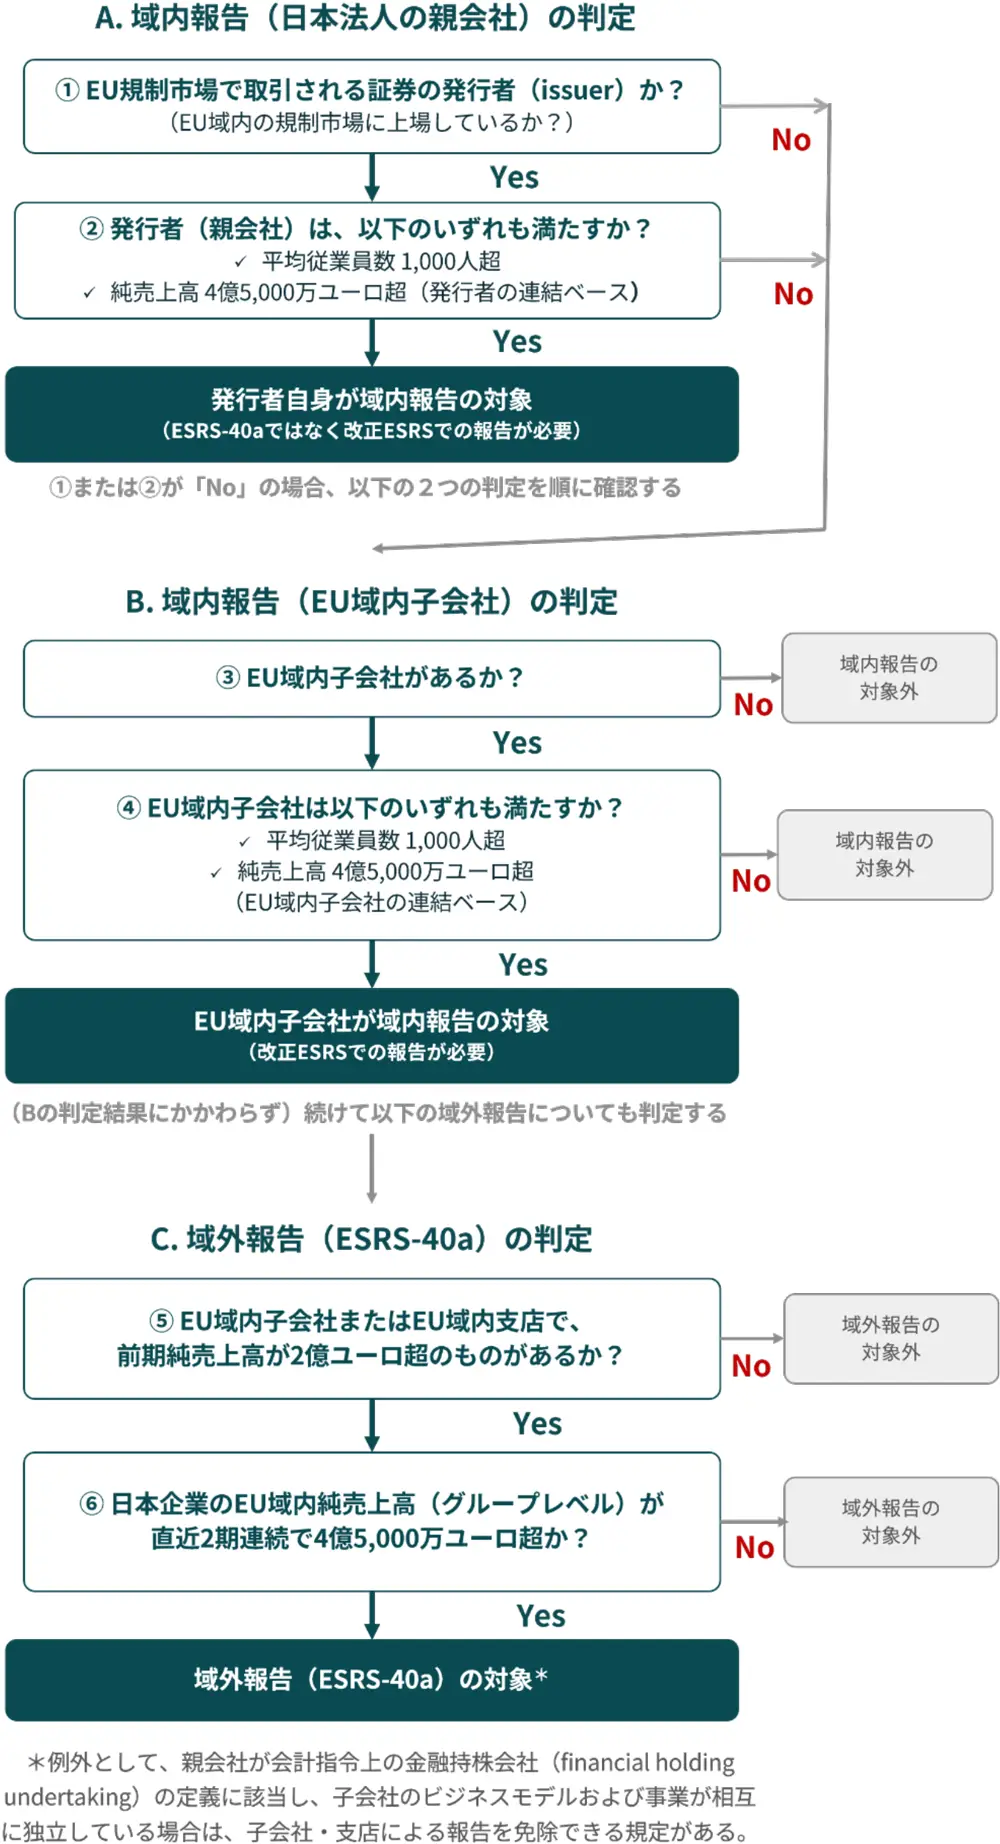 Zeroboard Create based on SSBJ materials *5)
Mixed Approach – Is it Possible to Limit it to "EU-Related Impacts"?
Another feature of ESRS-40a is the two options regarding reporting boundaries. One is the "global approach," which reports the global impact for all topics, and the other is the "mixed approach," which maintains global reporting for climate change (E1) while limiting reporting to "EU-related impacts" for other topics *1) .
A mixed approach is only permissible if meaningful identification of EU-related impacts is possible. EU-related impacts must include both (1) "customer-based components" linked to products and Service sold or provided (or reasonably assumed to be sold or provided) in the EU market, and (2) "location-based components" linked to business activity within the EU. In both cases, impacts may be attributed to suppliers or downstream distributors outside the EU, regardless of where the impact occurs. When calculating indicators, indicators common to both EU and non-EU businesses, such as Total emissions or total water intake by suppliers, must be apportioned between EU-related impacts and non-EU impacts. In doing so, a reasonable "allocation criterion" (such as an allocation key based on sales or production volume ratios) that takes into account the nature of the impact and geographical circumstances must be used.
The mixed approach was added at the request of the European Commission, and EFRAG itself was reportedly cautious about its introduction. In fact, during the discussions at EFRAG, concerns were raised about undermining fair competition with EU companies, the lack of comparability due to differences in the units of application, and the practical difficulties in identifying EU-related impacts and concerns about their assurance, and these have become key issues in the public comments. *4)
Key points of topic-specific disclosures: E1 is global, other are mixed.
The ESRS-40a standard structure consists of two cross-cutting standards (ESRS-40a 1: General Requirements, ESRS-40a 2: General Disclosures) and 10 topic-specific standards (E1-E5, S1-S4, G1), and the architecture itself remains unchanged from the revised ESRS *1) (Figure 3).
E1 (Climate Change) is excluded from the mixed approach and global disclosure is always required. E1-2 (Climate-Related Risks and Scenario Analysis) and E1-3 (Resilience) of the revised ESRS are deleted as they fall under RORD, while disclosure on a group-consolidated basis is still required for transition plans (E1-1), total Scope 1 1, 2, and 3 emission amount(E1-8), and GHG removals and carbon credits (E1-9). Topics from E2 (Pollution) onward are subject to the mixed approach, and for example, in E2, downstream impacts of products Manufacturing outside the EU and sold within the EU may be included in "EU-related" in addition to the company's own operations within the EU. In S1 (Our Workers), the scope of application of the mixed approach (workers at the company's operations located in the EU and workers outside the EU involved in the production of products and Service for the EU market) has been newly defined, and whether disclosure of EU and non-EU breakdowns regarding safety and health and gender wage gaps is required is a point of discussion in the public comments *4) .
Figure 3: Architecture of the revised ESRS and ESRS-40a disclosure items
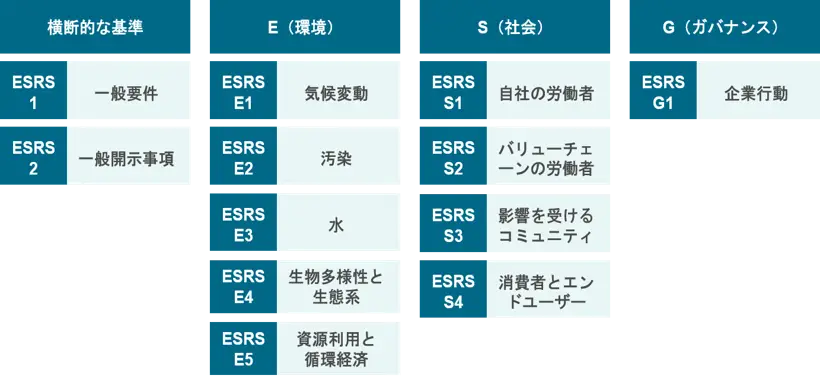 Zeroboard Create based on ESRS-40a ED *1)In the discussion, the author advised, "When adopting a hybrid approach, data segmentation by customer and location is required. Japanese companies often have detailed data on their domestic activity, but data collection is often insufficient for other regions, let alone their own supply chains. Establishing a data collection system and a sophisticated database in cooperation with local subsidiaries and branches in the EU is the best way to ultimately address SSBJ requirements."
Interoperability – How IFRS Standards and SSBJ should engage with GRI
For companies already reporting under IFRS S (ISSB) or SSBJ standards, avoiding duplicate reporting is a major concern. Under ESRS-40a ED, if certain conditions are met (such as being incorporated from mandatory reporting, clearly identifying ESRS-40a data points, being published at the same time as or earlier than the ESRS-40a report, Create and translated in an official EU language, ensuring the same level of quality, and clearly indicating its location in the table of contents), reporting that avoids duplicate disclosure by referencing IFRS S/SSBJ reports (such as securities reports) is permitted. In the climate sector in particular, it is possible to meet ESRS-40a requirements by supplementing ESRS-40a-specific items (such as Energy mix, locked-in emissions *6 , consistency with the 1.5°C target, bio-based emissions, removals, and information on fossil fuel operations) in addition to IFRS S2 or SSBJ climate-related disclosure standards. An option is also available to disclose ESRS-40a and jurisdictional standards in a single report while clearly identifying them *1) .
On the other hand, attention must be paid to its relationship with the GRI Standards. If a parent company outside the EU Create a consolidated report using standards legally recognized as equivalent by the European Commission, its subsidiaries and branches within the EU may be exempt from Create and submitting individual ESRS-40a reports. However, as of the time of writing, the European Commission has not officially recognized the GRI as this "equivalent" standard *4) . Mr. Kataoka stated, "When you read the Contents of ESRS-40a in detail, you will find that there is overlap with items that are familiar from the GRI. It is necessary to lobby the European Commission through public comments and other means so that the GRI, which is being implemented by many Japanese companies and Asian countries, will be considered legally equivalent."
Voluntary standards – setting limits on supplier compliance.
Simultaneously with the revised ESRS, a voluntary disclosure standard for companies with fewer than 1,000 employees, the "Voluntary Standard" (a revision of the Voluntary Reporting Standard for Small and Medium-Sized Enterprises - VSME), was also adopted as delegated rule C(2026)5011 *7) . This standard also functions as the basis for the "value chain cap," which limits the scope of information that companies subject to CSRD can request from small and medium-sized enterprises in their value chain to the Contents of this voluntary standard *8) . The structure consists of two layers: the minimum set of "Basic modules" (B1-B11: Energy/GHG, pollution, water, waste, employee characteristics, occupational accidents, wages, etc.) and the "Comprehensive modules" (C1-C9: climate transition plans, climate risk, human rights policies, governance diversity, etc.) that respond to additional requests from investors, banks, and business partners (Table 1). The application of the value chain cap will be in line with the application of the main text of the revised ESRS, starting with the 2027 fiscal year report.
Table 1: Disclosure items of voluntary standards
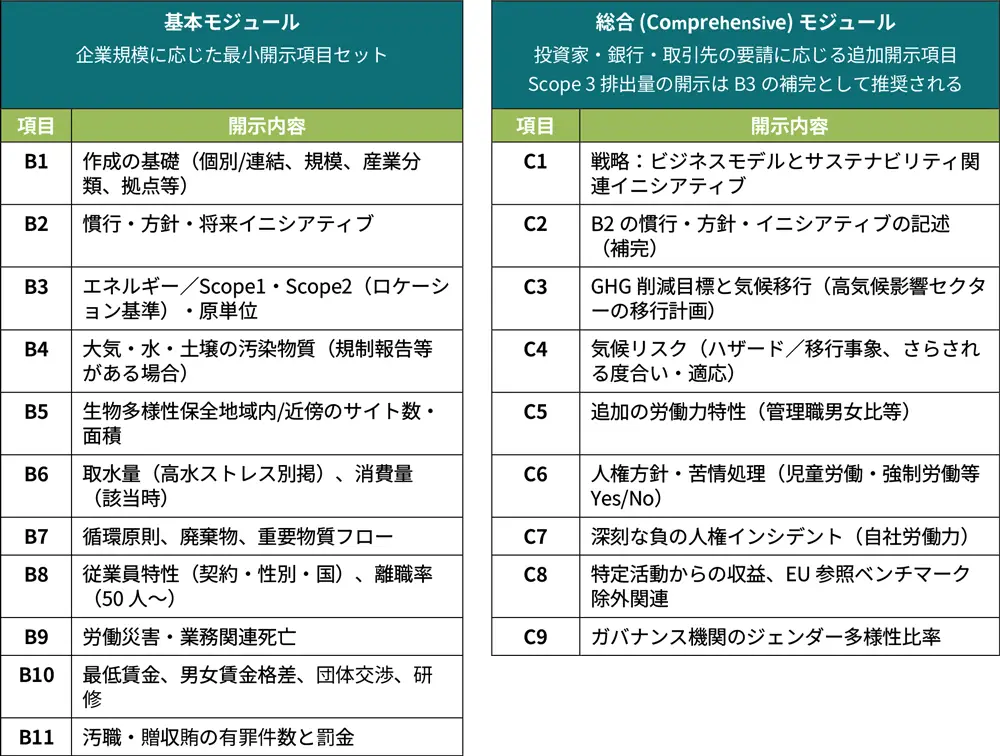 Zeroboard Create based on European Delegated Regulation C(2026)5011 *7)
There are three main ways in which Japanese companies can utilize their voluntary standards. Firstly, if European business partners request excessive self-assessment questionnaires (SAQs), these standards can be used as a basis for refusal or as an upper limit on what information is sufficient. Secondly, there is a way to respond to requests from investors, banks, and customers in accordance with the voluntary standards. Thirdly, by aligning the design of supplier surveys with the voluntary standards, large companies can streamline the surveys themselves. In the discussion, Mr. Kataoka commented, "Many Company are still troubled by the large amount of information that their business partners request individually. The definition of a cap and standard items that indicate what is sufficient is welcome and will give them the power to push back against excessive demands."
Practical response points for Japanese companies
Finally, let's summarize the practical points to confirm. First, it is necessary to determine whether your company falls within the scope of ESRS. Two thresholds need to be monitored: net sales within the EU exceeding €450 million (for two consecutive periods) and sales of subsidiaries and branches within the EU exceeding €200 million. Next, consider whether to base your reporting on ESRS-40a, the revised ESRS, or an equivalent standard. Choosing the revised ESRS allows you to omit the obligation to report separately for subsidiaries within the EU. If reporting under ESRS-40a, the key is whether to adopt a mixed approach and, if so, how to extract EU-related information. Next, it is necessary to reorganize existing disclosures such as SSBJ, IFRS S, GRI, and TNFD, and to organize the reference policies. It is also essential to prepare governance aspects such as redesigning supplier requests and customer responses based on voluntary standards (value chain caps), addressing limited assurance, internal controls, and data collection systems and authority from group Company.
Table 2: Comparison of Revised ESRS, ESRS-40a, and Voluntary Standards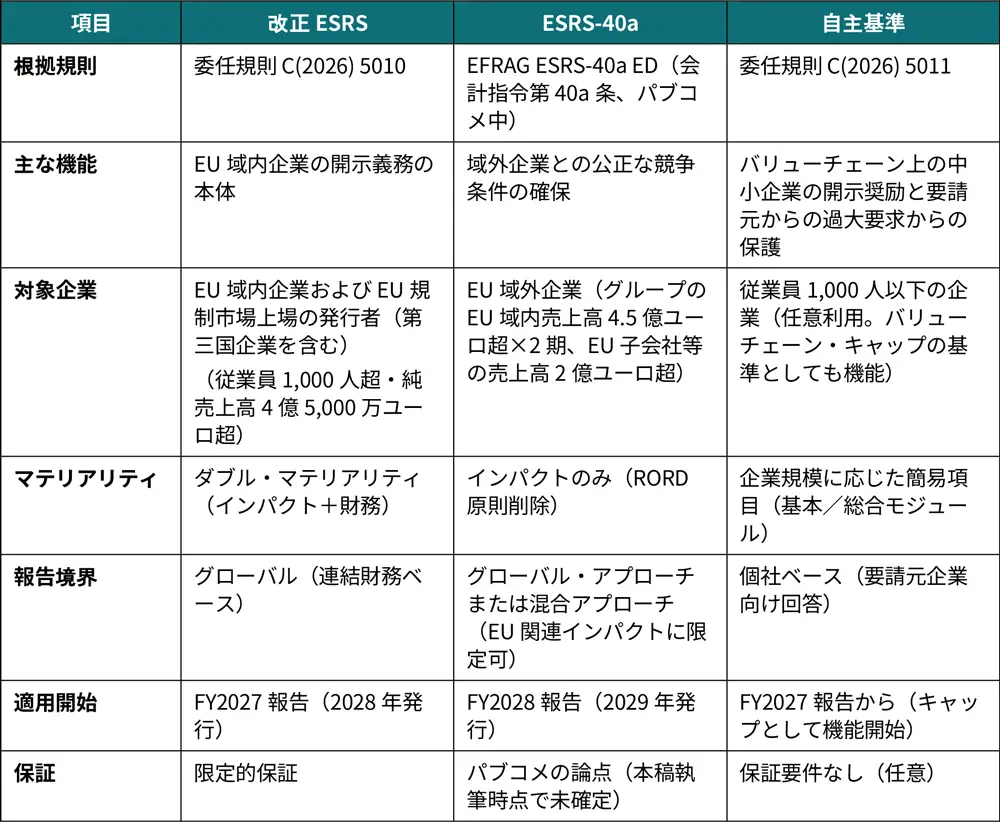 Zeroboard Create
Going forward, ESRS-40a ED will be reviewed based on public comments, field tests by voluntary participating companies, and cost-benefit analyses, focusing on the appropriateness of applying EU laws and regulations to non-EU companies (fair competition conditions), the merits of a mixed approach, the identifiability of EU-related impacts, and its equivalence to GRI standards. EFRAG is scheduled to provide technical advice to the European Commission in January 2027. Based on this, the European Commission will conduct further public comments and make final adjustments before adopting the delegated regulation *2) .
Even if the number of Japanese companies that may be subject to ESRS-40a remains at around 100 to 150, beyond that lies a broader group of companies that will be required to provide data by their EU trading partners, and a group of supplier companies that will, for the first time, receive concrete "upper limits" on disclosure in the form of voluntary standards. The simplification of ESRS, the assurance of fair competition for non-EU companies through ESRS-40a, and the reduction of the burden on value chains through voluntary standards should be understood as a three-tiered structure (Table 2). With the public comment deadline of October 31, it is desirable for Japanese companies and industry associations to convey practical issues to the European side.
At the end of the webinar, Mr. Kataoka offered words of encouragement, saying, "Japanese companies are diligent and tend to respond sincerely to what they are told, but I hope they will always be shrewd and promote sustainability initiatives that are effective for their own company and for society."
*1) European Financial Reporting Advisory Group (EFRAG), ESRS for Certain Non-EU Undertakings in Accordance with Article 40a of the Accounting Directive, Exposure Draft, 23 July 2026. https://www.efrag.org/en/projects/esrs-for-certain-noneu-undertakings-in-accordance-with-article-40a-of-the-accounting
*2) EFRAG, “EFRAG launches public consultation on the ESRS-40a Exposure Draft for Certain Non-EU Undertakings”, news release. 23 July 2026. https://www.efrag.org/en/news-and-calendar/news/efrag-launches-public-consultation-on-the-esrs40a-exposure-draft-for-certain-noneu-undertakings
*3) European Commission, “Commission adopts revised sustainability reporting standards to reduce administrative burdens for EU businesses while maintaining high-quality disclosures”, press release. 3 July 2026. https://finance.ec.europa.eu/news/commission-adopts-revised-sustainability-reporting-standards-reduce-administrative-burdens-eu-2026-07-03_en
*4) EFRAG, ESRS for Certain Non-EU Undertakings in Accordance with Article 40a of the Accounting Directive (ESRS-40a), webinar presentation, 22 July 2026. https://www.efrag.org/sites/default/files/media/document/2026-07/22%20July%202026%20-%20ESRS-40a%20Exposure%20Draft%20-%20EFRAG%20PPT.pdf
*5) Sustainability Standards Board of Japan (SSBJ), "Introduction to the SSBJ Secretariat's overview of the Exposure Draft of ESRS-40a," Seminar materials, August 26, 2026 https://www.ssb-j.jp/jp/wp-content/uploads/sites/6/2026_0826.pdf
*6) GHG emissions that are expected to continue to occur in the future as long as existing facilities and assets continue to operate, and which may hinder the achievement of reduction targets or increase transition risks.
*7) European Commission, Commission Delegated Regulation C(2026) 5011 final establishing a Voluntary Standard for sustainability reporting by non-listed micro, small and medium-sized undertakings. 3 July 2026. https://ec.europa.eu/finance/docs/level-2-measures/csrd-delegated-act-2026-5011_en.pdf
*8) European Union, Directive (EU) 2026/470 of the European Parliament and of the Council of 24 February 2026 amending Directives 2006/43/EC, 2013/34/EU, (EU) 2022/2464 and (EU) 2024/1760 as regards certain corporate sustainability reporting and due diligence requirements, Official Journal of the European Union, 26 February 2026. https://eur-lex.europa.eu/legal-content/EN/TXT/HTML/?uri=OJ%3AL_202600470
Related articles
-
Deciphering the Exposure Draft of the EU Disclosure Standard "ESRS-40a" for Non-EU Companies - Limitations on Impact and Value Chain Voluntary Standards (Public Comment Period Ends October 31)
-
Public comments on the revised GHG protocol Scope 2 have been released — Multiple methods to be considered due to disagreements over hourly matching, etc.
-
Measurement and Disclosure for Nature Positive "Implementation" - The Kumamoto Summit Showcased the Two Pillars of Impact and "Dependence"
-
What is Supply Chain Security? An explanation of implementation design and SCS evaluation systems to prevent procurement disruption risks.
Ongoing Webinars
-
[Recorded Broadcast] This is not someone else's problem—Why supply chains are becoming a management Issue: An interview with Kenji Fuma on how companies could have prepared and acted.
Location: Online (Zoom)Participation fee: Free -
This is not someone else's problem—Why supply chains are becoming a management Issue: An interview with Kenji Fuma on how companies could have prepared and acted.
Location: Online (Zoom)Participation fee: Free -
[Sponsored by Keidanren] What can AI do to make society sustainable?
~ Zeroboard's 5th Anniversary Conference "The Zeroboard Day 2026"~Location: Online (Zoom) *Archive streaming will be available at a later date.Participation fee: Free -
[Sponsored by Keidanren] The Essence of Sustainability Management Supported by the Front Lines: The Zeroboard 5th Anniversary Conference "The Zeroboard Day 2026"
Location: Online (Zoom) *Archive streaming will be available at a later date.Participation fee: Free
-
Deciphering the Exposure Draft of ESRS-40a, the Disclosure Standard for Non-EU Companies: Limitations on Impact and Value Chain Voluntary Standards (Public Comment Period Ends October 31)
-
Public comments on the revised GHG protocol Scope 2 have been released — Multiple methods to be considered due to disagreements over hourly matching, etc.
-
Measurement and Disclosure for Nature Positive "Implementation"—The Kumamoto Summit Revealed the Two Pillars of Impact and "Dependence"
-
What is Supply Chain Security? An explanation of implementation design and SCS evaluation systems to prevent procurement disruption risks.
-
Feeling the limitations of managing supplier surveys (CSR surveys) with Excel? How SAQ systemization can solve these problems.