Measurement and Disclosure for Nature Positive "Implementation"—The Kumamoto Summit Revealed the Two Pillars of Impact and "Dependence"


Vice Chair of the Global Sustainability Standards Board (GSSB)
Member of the GHG Protocol Expert Working Group (TWG)
Director of Zeroboard Research Institute Tomoo Machiba
August 1, 2026
The 2nd Global Nature Positive Summit (GNPS2026) was held in Kumamoto City, the "City of Water," for two days from July 14th to 15th, 2026, and concluded with the adoption of the "Kumamoto Declaration" *1) . This rare international meeting in Japan attracted approximately 2,700 attendees, mainly from companies and Financial Institution both domestically and internationally, and served as a forum to shift the focus of discussion from "ideals to action" toward the 2030 targets of the Kunming-Montreal Framework for Biodiversity (GBF) *2) . I attended the summit representing the Global Sustainability Standards Board (GSSB) of the Global Reporting Initiative (GRI), and spoke at the plenary session on the interoperability of natural capital-related standards. I also participated in exchanges with UN agencies and international organizations, and, together with Tony Goldner, CEO of the Task Force on Nature-Related Financial Disclosures (TNFD), planned and implemented informal dialogues with Japanese companies. This paper will discuss the implementation phase of the Nature Positivity initiative outlined at the summit, and the necessity of directly addressing dependencies on natural capital in addition to impact, when considering corporate financial risks and opportunities arising from biodiversity.
The summit demonstrated a shift towards "action."
GNPS2026, following its inaugural event in Sydney in 2024, was co-hosted by the Nature Positive Initiative (NPI), an international coalition of conservation organizations, research institutions, and businesses, and the International Union for Conservation of Nature Japan Committee (IUCN-J). The venue, Kumamoto Castle Hall, was filled with domestic and international leaders, including Her Imperial Highness Princess Hisako Takamado, Honorary President of BirdLife International, and Paul Polman, former CEO of Unilever, who engaged in multifaceted discussions on corporate strategy, finance, technology, marine conservation, and watershed stewardship. The accompanying exhibition, "NATURE TECH!", was packed with local students, creating a lively and bustling atmosphere. The Kumamoto Declaration, announced at the closing of the conference, was endorsed by 85 organizations, including 41 private companies. It views the transition to a nature-positive economy not as a cost but as an investment, and advocates for consistency in measurement, evaluation, and reporting, integration of nature-based solutions (NbS) with decarbonization, and a just transition, demonstrating a commitment to connecting these efforts to the 17th Conference of the Parties to the Convention on Biological Diversity (COP17) to be held in Yerevan, the capital of Armenia, in October 2026. *3)*4)
The host city of Kumamoto itself demonstrated that dependence cannot be dismissed as mere abstract theory. As the "world's leading groundwater city," which relies entirely on groundwater for its tap water supply, it has built up efforts in upstream water recharge and watershed collaboration, while the influx of semiconductor-related Industry is presenting a new burden on water resources *2) . A perspective that views forests, rivers, farmland, and cities as a single landscape is necessary, and the results of nature positivity are insufficient with only on-site measures by individual companies. At the summit, water risks in the technology sector and watershed-scale water stewardship (water resource management and conservation) were discussed, and opinions were exchanged regarding the sustainable use of natural resources and the minimization of their burden. I felt that the true value of the summit lay not so much in the declaration itself, but in the fact that companies, investors, and standard- Settings bodies began to concretely define what to measure, what to disclose, and how to connect that to capital allocation that supports sustainable activity.
"Dependence" as a prerequisite for risks and opportunities
In discussions on nature-related disclosures, GBF's 2030 Target 15 encourages governments to require companies to assess and disclose risks, dependencies, and impacts related to biodiversity *5) , and TNFD treats dependencies, impacts, and risks and opportunities (DIRO) as a whole *6) . However, IFRS Sustainability Disclosure Standard S1 (General Requirements) and the Sustainability Standards Board of Japan (SSBJ) General Disclosure Standard only explain that a company's dependency on resources and relationships in its value chain is related to risks and opportunities. The European Sustainability Reporting Standard (ESRS) defines dependency in Annex II as "a state in which business processes rely on natural, human, and social resources" and requires consideration in double materiality assessments, but does not define a standard indicator specifically for dependency in E4 (Biodiversity). GRI has long been responsible for transparency regarding the impacts that organizations have on the economy, the environment, and people, and dependency has fallen into a gap in the global reporting system *7) .
The specifics of dependence become clearer when you consider the industry. For a beverage manufacturer, it's the volume and quality of water in the river basin; for food and agriculture, it's pollinating insects and soil; for semiconductors and data centers, it's water for Manufacturing and cooling; for paper and timber, it's forest resources; and for fisheries and shipping, it's marine ecosystems. For Financial Institution, these dependencies become exposure to the entire portfolio through investment and loan recipients and insurance contracts. If these dependencies waver, it can lead to financial impacts such as operational shutdowns, increased procurement costs, and changes in insurance and capital costs. On the other hand, investments in water resource conservation, regenerative agriculture, and sustainable procurement can offer both risk reduction and business opportunities. In light of this situation, GRI, TNFD, and the UN Principles for Responsible Investment (PRI) co-hosted an informal meeting on the morning of the second day of the summit to hear opinions and discuss the merits of more systematically incorporating dependencies into disclosures, inviting domestic investors, business Company, guarantee practitioners, and environmental and policy stakeholders.
At the beginning of the meeting, TNFD CEO Goldner indicated that dependency is already positioned in the TNFD Recommendations and GBF Target 15, that dependency assessment is practically feasible in early TNFD disclosure practices and has led to corporate actions, and that investor stewardship is showing increasing interest in dependency. He then asked attendees about the possibility of more explicitly addressing dependency in the GRI Standards, which have a global foundation in impact disclosure, from the perspective of aligning the entire reporting system. Esther Ann of Singapore-based developer Citi Developments (member of the GRI Supervisory Board), who also participated in the London Climate Week meeting in June, spoke from the perspective of a company that considered dependency, stating that considering dependency practically connects "impact transparency" and double materiality reporting of "financial risk-opportunity and value information," and that the TNFD's LEAP (Discovery, Diagnosis, Assessment, Preparedness) approach *8) is useful not only for risks but also for discovering nature-positive deals that are linked to opportunities and finance.
In the subsequent open discussion, the practical aspects of dependency disclosure were debated without identifying the speakers. Dependence and impact are observable facts rooted in the past and present, while risks and opportunities are future projections based on assumptions and scenarios. Therefore, dependency information should not be merely an addendum to risk disclosure, but rather a foundation for users to verify the validity of the financial impacts anticipated by management. Investors also seek not only packaged risk conclusions, but also concrete facts such as location, raw materials, and the degree of dependency in sales. Translating dependencies and impacts measured in natural units into financial impacts in monetary units is both a challenge and a focal point of interest. While physical risks such as water and procurement are often already understood on the ground, there is still a distance to treating dependencies as a capital allocation Issue for the board of directors, and the view was expressed that transparency in the process of how dependencies were identified using LEAP, etc., is useful alongside indicators. Standardization is necessary for comparison, but caution was shared against excessive uniformity that erases the ecological context of sectors and locations.
In a panel discussion at the plenary session, the author explained the interoperability of GRI and TNFD as follows: Although the two have different objectives, they are complementary, and by using biodiversity information that a company has compiled once, GRI can be used for impacts on nature, and TNFD can be used for risks, opportunities (and dependencies) to the business, thereby supporting both sides of double materiality without duplicate reporting *9) . Ensuring that dependencies are not left out is the next practical Issue in bringing this interoperability closer to its complete form. In summary of the dialogue, there was a shared direction that dependency disclosure should not replace impacts or risks and opportunities, but should become a more explicit and structural component within the global reporting system.
The positioning of the "State of Nature" (SoN) index
Meanwhile, the NPI, a co-organizer of the summit, is working to establish consensus on the "State of Nature" (SoN) index as a common measure for measuring natural loss and recovery. Using 2020 as the base year, with a timeline of halting or reversing losses by 2030 and recovery by 2050, they have been developing draft indicators, mainly for land areas, and have progressed to a pilot in 2025 and a final consultation in February- March 2026 *10) . Japanese companies such as Kirin Holdings and Oji Holdings also participated in the pilot *11) . While there is a common indicator of emission amount for climate change, there are more than several hundred indicators for nature, and there is a lack of common understanding of what constitutes recovery, and SoN is an attempt to fill that gap. Summit participants had been looking forward to the announcement in Kumamoto, but the formal positioning of the full-scale determination of the indicator set and its integration into the existing framework was postponed to COP17.
The key here is the division of roles between State of Nature (SoN) and corporate disclosure. SoN shows changes in the state of nature itself, at the site, landscape, and even globally. The difference from the base year's state measures whether nature is recovering or continuing to be lost. Corporate impact shows the pathways of negative (or positive) contributions to that state, while dependency shows the pathways of vulnerability to ecosystem Service and natural capital on which the business relies. Risks and opportunities manifest as the financial impacts of these pathways on revenue, costs, asset value, and capital raising. By defining baselines and differences, SoN can more objectively demonstrate how much a company's activity and investments contribute to the recovery of nature at a particular site or landscape. SoN is not merely a successor to TNFD, but its incorporation into TNFD, GRI, and Science Based Targets for Nature (SBTs) *12) is being discussed, and it will be a "component" for making nature state assessments more substantive *2) . It is rational to first prepare field data and evaluation processes such as LEAP, so that a common standard called SoN can be established and connected once it is finalized. Considering that terrestrial areas are ahead and freshwater and marine areas are still developing, SoN should be treated not as a finished product, but as a framework that is still evolving.
Intersection with TISFD—the same skeletal structure for "people"
This framework of "impact and dependence as facts" and "risk and opportunity as judgment" is not limited to the theme of biodiversity. The Task Force on Inequality and Social Financial Disclosures (TISFD), which published beta version 0.1 in May 2026, started with the "State of People" and clearly articulated in the "IDRO" framework a logic that connects the impact on human rights and inequality with dependence on skills, labor force, and social acceptance to risks and opportunities at the organizational and systemic levels *13) . The interdependence of environmental degradation exacerbating human rights violations and inequality, and inequality undermining social support for the green transition, is also positioned as a premise for integrated risk management (Figure). This aligns with the Kumamoto Declaration's mention of a just transition and a holistic approach.
Figure: Relationship between Dependency, Impact, and Financial Risks/Opportunities as illustrated by TNFD and TISFD
Left diagram: Zeroboard Create based on TNFD *6) (see Figure 11 on page 29), Right diagram: TISFD *13)
For companies, it is crucial to understand "what they depend on and how they affect it" across climate, nature, and society, rather than treating TNFD and TISFD as separate compliance issues, using the same data infrastructure and governance framework. With the expansion of human capital disclosures in securities reports and the parallel implementation of disclosure regulations such as IFRS S/SSBJ, SASB, GRI, and CSRD/ESRS, establishing the common language of IDRO/DIRO within the organization early on will actually reduce future disclosure burdens. Just as mandatory climate disclosures have led to the establishment of organizational structures, companies that have a system in place to "measure, translate, and discuss at the board of directors" for nature will be stronger in the face of future regulations and investor demands.
Implications for Japanese companies
Regarding dependencies and Systems of Networks (SoN), Japanese companies should prioritize the following four points. First, instead of limiting dependencies to abstract policies at headquarters, they should identify them at the location, raw material, and supplier level and try to link them to sales and operations. For example, at a granular level such as "the watershed on which the main factory draws its water" or "what percentage of sales depend on specific agricultural products or marine areas." Second, instead of creating information for each criterion, they should design the system to use data entered collectively through the lenses of each DIRO (Diagnostic and Industrial Research Organization). Third, without waiting for the final confirmation of SoN, they should organize existing water, land use, and biodiversity data as pathways from the "natural state." Fourth, with TISFD (Third-Party Science and Development) discussions in mind, they should begin mapping dependencies on natural and human capital across the entire system, utilizing the framework of integrated reporting. By doing so, they can prepare to respond to dependency and SoN disclosures without incurring additional time and effort.
Following Kumamoto, the next summit is scheduled to be held in India, and progress on GBF implementation will be rigorously scrutinized at COP17. As collaborative management of rural areas and watersheds has demonstrated, prosperity rests on a healthy ecosystem and the relationship between the region and the community. Organizational resilience is similar; nature positivity becomes a measurable management Issue only when it considers not only financial performance but also the impact on and dependence on people and nature. It is also important to note that in third-party assurance and investor dialogue, explanations of narratives and specific processes will be demanded in addition to numerical data.
*1) Nikkei BP "Global Nature Positive Summit 2026" website
https://events.nikkeibp.co.jp/event/2026/GNPS_jp*2) Naoki Adachi, "From Ideal to Action: What Will Be Asked at the Kumamoto Global Nature Positive Summit," Sustainable Brands Japan, July 13, 2026.
https://www.sustainablebrands.jp/news/1311169*3) Takahiro Soma, "85 Companies Endorse Nature Positive 'Kumamoto Declaration,' Encouraging Action Towards Realization in 2030," Nikkei Business Online, July 16, 2026.
https://business.nikkei.com/atcl/gen/19/00896/071500014*4) Tourism Economy Newspaper, "Global Nature Positive Summit 2026 Concludes,"July 21, 2026.
https://www.kankokeizai.com/2607211130kks*5) Ministry of the Environment, "Kunming-Montreal Biodiversity Framework" page
https://www.env.go.jp/nature/biodiversity/kmgbf.html*6) Taskforce on Nature-related Financial Disclosures (TNFD), "Recommendations of the Taskforce on Nature-related Financial Disclosures" (Japanese version), September 2023.
https://tnfd.global/wp-content/uploads/2024/02/自然関連財情報交訳作業隊のおすすめ言_2023.pdf*7) TNFD, “TNFD responds to ESRS consultation”, 5 June 2026.
https://tnfd.global/tnfd-responds-to-esrs-consultation/*8) Ministry of the Environment, "Explanation of LEAP/ TNFD," Workshop on Nature-Related Financial Disclosure (Advanced Edition), 1st Session, November 29, 2023.
https://www.env.go.jp/content/000178847.pdf*9) Global Reporting Initiative (GRI), “Accountability for impacts is essential to secure a nature-positive future”, press release, 16 July 2026.
https://www.globalreporting.org/news/news-center/accountability-for-impacts-is-essential-to-secure-a-nature-positive-future*10) Nature Positive Initiative (NPI), Consultation Brief: Finalisingconsensus on a universal state of nature metrics framework, 11 February 2026.
https://www.naturepositive.org/app/uploads/2026/02/Consultation-Brief_State-of-Nature-Metrics_Feb26.pptx.pdf>*11) Kaori Fujita, "Visualizing the 'Natural State' of Giraffes and Princes with Indicators: Preparing for TNFD Disclosure," Nikkei Business Online, June 23, 2026.
https://business.nikkei.com/atcl/gen/19/00896/061900004*12) Science-based Targets Network (SBTN), "Nature SBTs Corporate Manual - Settings Science-Based Targets Related to Nature" (Japanese version), February 2025.
https://sciencebasedtargetsnetwork.org/wp-content/uploads/2025/02/ SBTN-Corporate-Manual-Japanese-Feb2025.pdf*13) Taskforce on Inequality and Social-related Financial Disclosures (TISFD), The TISFD Framework: Recommendations on disclosure of people-related information by businesses and financial institutions, Beta Version 0.1, 26 May 2026.
https://www.tisfd.org/frameworks/tisfd-framework-beta-version-0-1
Related articles
-
Deciphering the Exposure Draft of the EU Disclosure Standard "ESRS-40a" for Non-EU Companies - Limitations on Impact and Value Chain Voluntary Standards (Public Comment Period Ends October 31)
-
Public comments on the revised GHG protocol Scope 2 have been released — Multiple methods to be considered due to disagreements over hourly matching, etc.
-
Measurement and Disclosure for Nature Positive "Implementation" - The Kumamoto Summit Showcased the Two Pillars of Impact and "Dependence"
-
What is Supply Chain Security? An explanation of implementation design and SCS evaluation systems to prevent procurement disruption risks.
Ongoing Webinars
-
[Recorded Broadcast] This is not someone else's problem—Why supply chains are becoming a management Issue: An interview with Kenji Fuma on how companies could have prepared and acted.
Location: Online (Zoom)Participation fee: Free -
This is not someone else's problem—Why supply chains are becoming a management Issue: An interview with Kenji Fuma on how companies could have prepared and acted.
Location: Online (Zoom)Participation fee: Free -
[Sponsored by Keidanren] What can AI do to make society sustainable?
~ Zeroboard's 5th Anniversary Conference "The Zeroboard Day 2026"~Location: Online (Zoom) *Archive streaming will be available at a later date.Participation fee: Free -
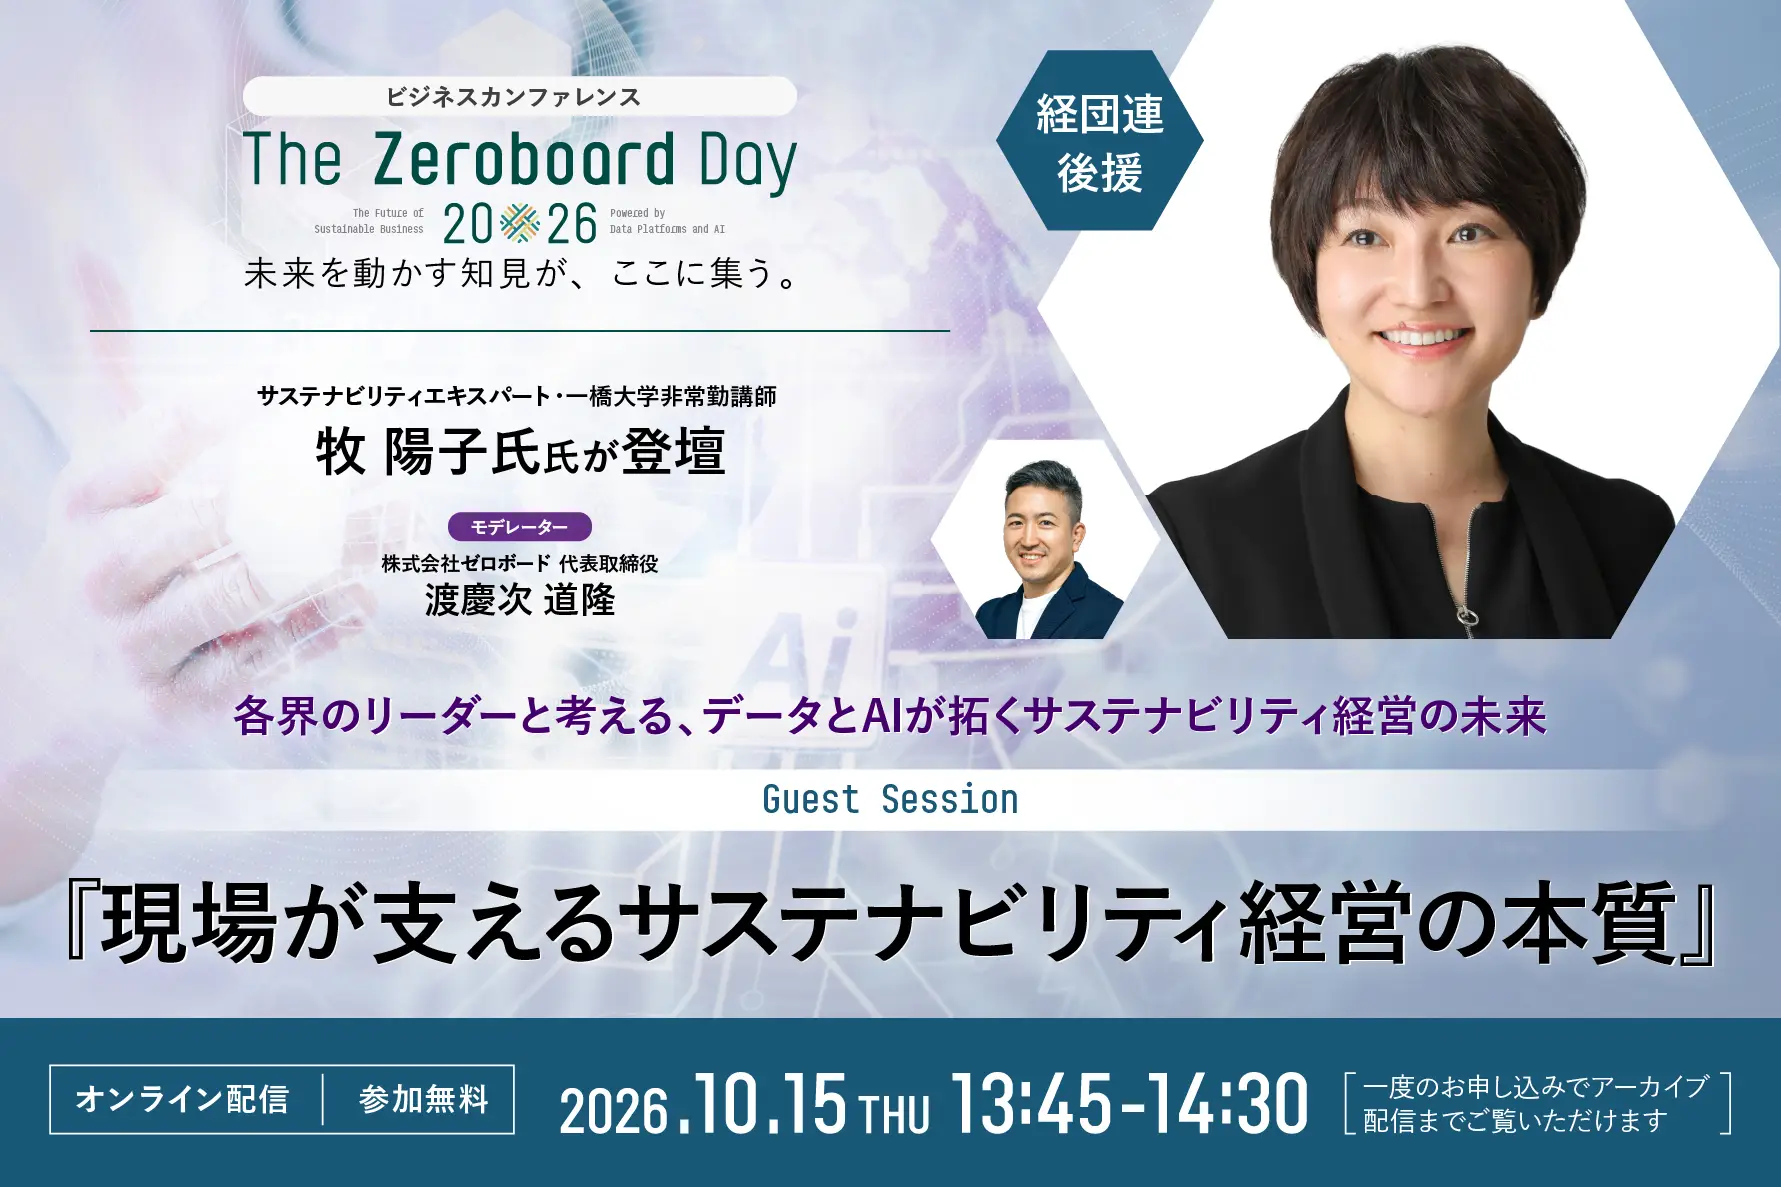
[Sponsored by Keidanren] The Essence of Sustainability Management Supported by the Front Lines: The Zeroboard 5th Anniversary Conference "The Zeroboard Day 2026"
Location: Online (Zoom) *Archive streaming will be available at a later date.Participation fee: Free
-
Deciphering the Exposure Draft of ESRS-40a, the Disclosure Standard for Non-EU Companies: Limitations on Impact and Value Chain Voluntary Standards (Public Comment Period Ends October 31)
-
Public comments on the revised GHG protocol Scope 2 have been released — Multiple methods to be considered due to disagreements over hourly matching, etc.
-
Measurement and Disclosure for Nature Positive "Implementation"—The Kumamoto Summit Revealed the Two Pillars of Impact and "Dependence"
-
What is Supply Chain Security? An explanation of implementation design and SCS evaluation systems to prevent procurement disruption risks.
-
Feeling the limitations of managing supplier surveys (CSR surveys) with Excel? How SAQ systemization can solve these problems.