TISFD releases first draft – Disclosure framework for "people" takes shape; public comments open until July 31.


Vice Chair of the Global Sustainability Standards Board (GSSB)
Member of the GHG Protocol Expert Working Group (TWG)
Director of Zeroboard Research Institute Tomoo Machiba
Following the development of disclosure frameworks by the Task Force on Climate-related Financial Disclosures (TCFD) for climate change and the Task Force on Natural-related Financial Disclosures (TNFD ) for natural capital, the Task Force on Inequality and Social -related Financial Disclosures (TISFD) published a "beta version 0.1" of its framework on May 26, 2026, and is conducting a public consultation (public comment) until July 31 *1) . The scope of information that investors seek beyond traditional financials is gradually expanding from "climate → nature → society," and this is an attempt to re-examine Issue such as the well-being and human rights of people inside and outside organizations, as well as inequality, in relation to the organization's short, medium, and long-term financial risks and opportunities. This article introduces the core concepts of TISFD and an overview of version 0.1, and summarizes the key points that Japanese companies should be aware of now.
What is TISFD? – Its origins and differences from TCFD and TNFD
TISFD is a global initiative to develop a disclosure framework for investors based on the recognition that social inequalities and human-related Issue can, in turn, affect the performance of companies and Financial Institution, investment results, and ultimately, the stability of the economy and markets. Initially, two task force concepts, "inequality-related" and "social-related," were merged and officially launched in September 2024 with more than 20 founding partners *2) . A key feature is the involvement of a wide range of stakeholders, including institutional investors such as the California Public Employees' Retirement System (CalPERS) and leading global corporations, as well as international organizations such as the OECD, ILO, and the UN Principles for Responsible Investment (PRI), and NGOs such as Oxfam *3) .
The TCFD was established in 2015 at the request of the Financial Stability Board (FSB) and promoted financial disclosure of climate risks led by the financial sector. The TNFD was launched in 2020, and a group of experts developed the intersection of natural capital and business. The TISFD inherits this lineage and shares a structure of four pillars: governance, strategy, risk management, and indicators and targets. However, the starting point of its establishment and the focus of its governance are different. The TISFD has four co-chairs representing business, labor, finance, and international organizations [7 High 1.1], clearly positioning human rights, labor, and inequality as internal Issue rather than external diseconomies, or issues outside the market. The steering committee, which is the decision-making body, consists of 25 members from Financial Institution, companies, and labor organizations in 15 countries, and Takeshi Kimura, Managing Executive Officer of Nippon Life Insurance, is the representative from Japan *4) .
Aiming to publish final recommendations in the second half of 2027.
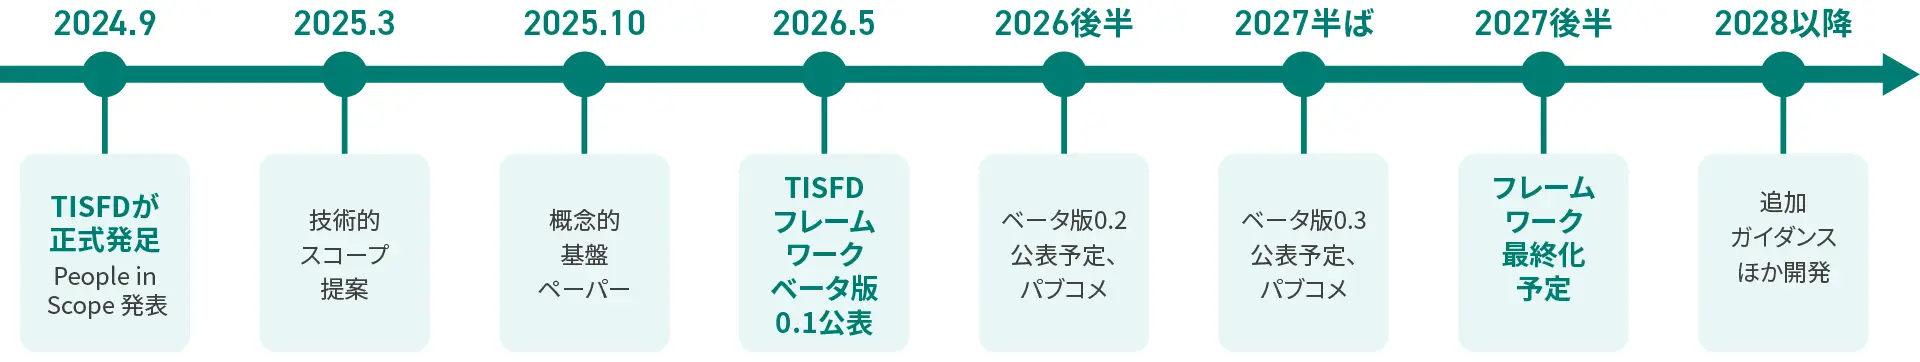
TISFD presented its scope, governance, and work plan in September 2024 (*3) , followed by a technical scope proposal in March 2025 (*5) , and a conceptual foundation paper in the fall of the same year (*6) . Beta development of the framework began in the latter half of 2025. Version 0.1, published this time, is the first stage of development and includes draft disclosure recommendations across three pillars: conceptual foundation, general requirements, and governance, strategy, impact, and risk management, as well as explanations of future development priority areas. The fourth pillar, recommendations for metrics and targets, and draft implementation guidance, has been postponed to the next version. After the public comment period, a pilot test will be conducted, with the aim of publishing version 0.2 in the latter half of 2026, version 0.3 in mid-2027, and the final recommendations in the latter half of 2027. The envisioned timeline is to encourage companies to recognize human rights and inequality risks within 1-2 years of the initial publication, to integrate the framework into regulations and standards within 2-3 years, and to achieve widespread application within 5-10 years (Figure 1).
Figure 1: Development schedule of the TISFD framework
 Zeroboard Create based on TISFD Framework (Beta Version 0.1) *1)
Basic concepts of human rights and inequality
TISFD's starting point is the "State of People." Human rights and labor rights are rights that enable all people to live with dignity, and companies have a responsibility to respect these. Well-being is a multifaceted concept that evaluates the quality of people's state, including health, safety , social connections , and work-life balance, and human rights are considered the minimum standard for well-being; well-being cannot be achieved without guaranteeing these. Human resources (resources accumulated by individuals such as knowledge, skills, and health) and social resources (trust, networks, and shared norms) are understood as "capital" that brings value to organizations, the economy, and society.
Inequality refers to how income, wealth, health, access to opportunity, etc., are distributed among people. TISFD distinguishes between horizontal inequality (disparities based on attributes such as gender, race, disability, and place of residence) and vertical inequality (disparities in the distribution of income, wealth, and health). Version 0.1 cites statistics showing that the wealthiest 10% account for more than half of global income, while over 1 billion workers do not earn a living wage, 2.1 billion are in precarious employment, and 40% of global employment may be affected by AI, demonstrating that structural vulnerabilities can be a breeding ground for corporate risk *7) .
Corporate activity, through wages, working conditions, procurement, capital allocation, product design, taxation, and activity, have both positive and negative "impacts" on people, intentionally and unintentionally, directly and indirectly. At the same time, it is argued that sustainable businesses cannot exist without "dependence" on human and social resources such as skilled workers, consumer trust, and social stability.
The positioning of risks and opportunities – their relationship to impact and dependence.
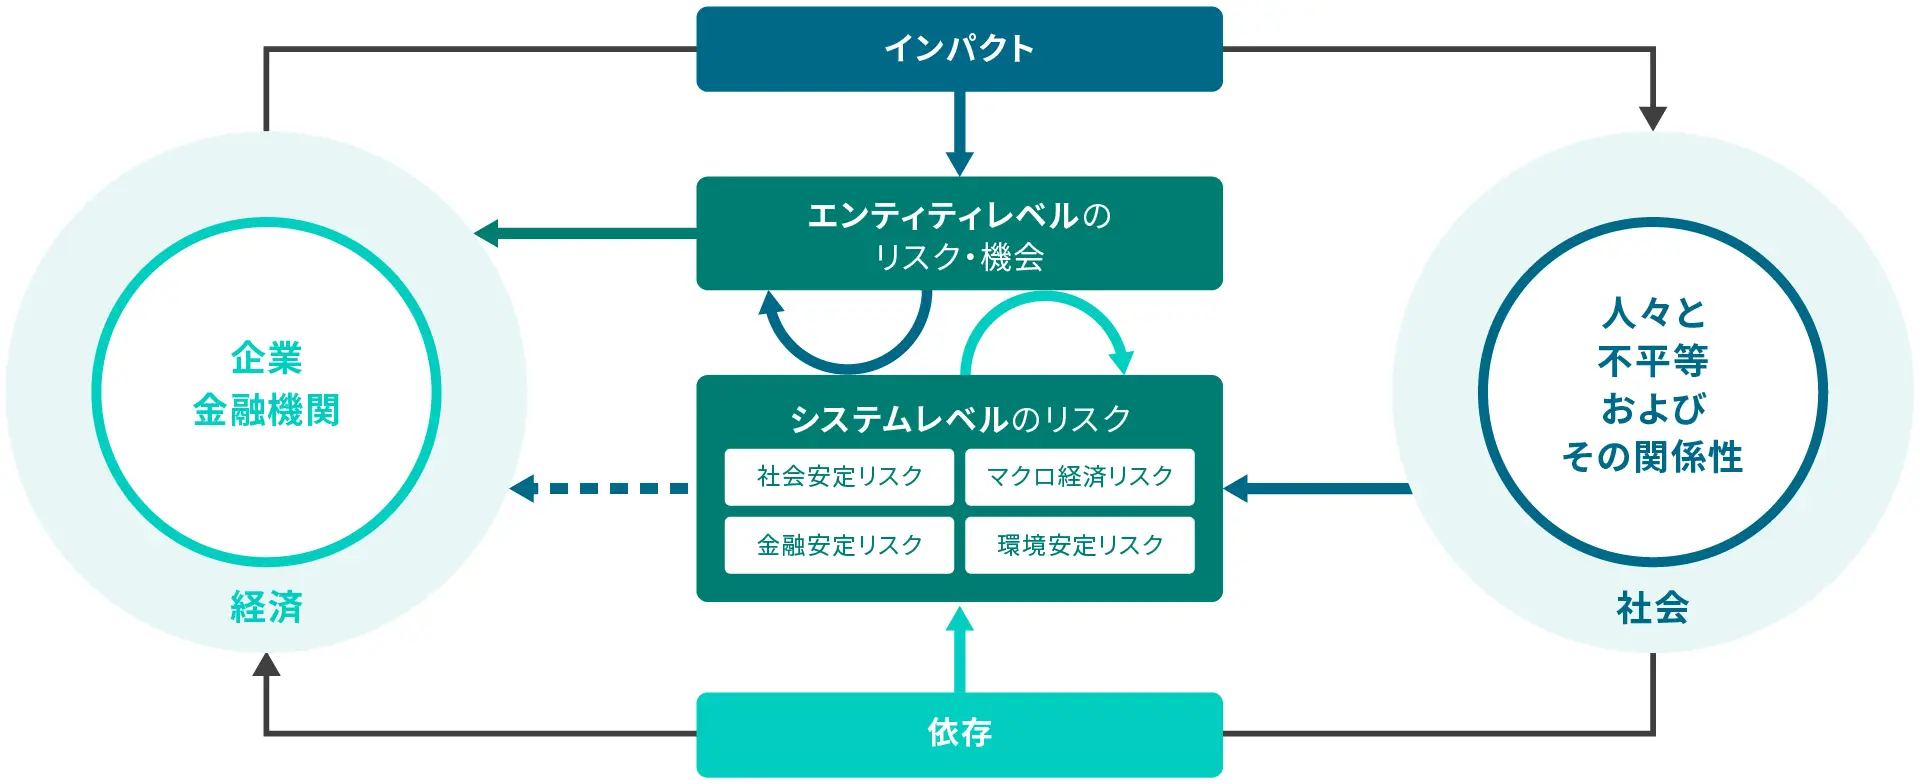
The core of TISFD's logic lies in the understanding of impact and dependence as the starting point for assessing risks and opportunities. Impact refers to the positive and negative effects that business activity, products and Service , and business relationships (such as suppliers and agents) have on people's human rights and inequalities. Dependence refers to the state in which organizational activity can only function if there is human and social capital, such as skills, labor, social acceptance from the community, and functioning Community and public Service . These impacts and dependencies influence revenue, costs, asset value, and capital-raising ability, creating financial risks or opportunities at the "entity (organization) level." Deficiencies in labor practices pose risks to operations, reputation, and legal regulations, while investment in people creates opportunities for productivity and innovation.
Furthermore, when the impacts of numerous companies and Financial Institution overlap, it can deepen inequality across society, leading to "system-level" risks such as weakened social cohesion, decreased productivity and demand, and instability in the macroeconomic and financial systems. For diversified investors, these risks cannot be mitigated by individual company investment decisions. Conversely, improvements in well-being, skills, and inclusion support sustainable growth and long-term value creation for society as a whole. TISFD is moving in the direction of requiring the disclosure of externalities that are important to investors as "system-related information" (see below), even if the pathway to financial impact at the entity level is indirect. The interdependence of climate change and biodiversity, where environmental degradation exacerbates human rights abuses and inequality, and inequality undermines social support for the green transition, is also positioned as a prerequisite for integrated risk management (Figure 2).
Figure 2: TISFD's view on the relationship between impact/dependence and risk/opportunity
 Zeroboard Create based on TISFD Framework (Beta Version 0.1) *1)
While the TCFD and the IFRS S and SSBJ standards based on it focus solely on financial risks and opportunities arising from environmental and social changes in the form of financial materiality, and lack any mention of the involvement of a company's own activity in the risks and opportunities, the TISFD takes an approach that takes into account the relationship between impact, dependence and risks and opportunities (IDRO), which can be seen as a result of reflecting the perspectives of a wide range of stakeholders, not just those in finance. Based on this, the TISFD emphasizes interoperability with IFRS S, GRI, and CSRD/ESRS standards and is designed as a "building block" that complements existing standards.
Version 0.1 overview- Basic Configuration and Disclosure Recommendations
Version 0.1 consists of: ① Business Case, ② Conceptual Foundation, ③ General Requirements, ④ Disclosure Recommendations, ⑤ Areas for Future Development, and ⑥ Stakeholder Engagement Methods. The disclosure recommendations are organized into four pillars, similar to the TCFD and TNFD, with a total of 12 draft items presented (Table 1). Under "Governance," the oversight structure of IDROs related to people, the role of management, and the stakeholder engagement process are disclosed. Under "Strategy," the interaction between identified IDROs and the business model/strategy, the financial impact, and the resilience of the strategy are described. Under "Impact and Risk Management," the process of identifying, evaluating, prioritizing, and monitoring IDROs in the company's business and value chain, and their integration into company-wide risk management are disclosed. "Metrics and Targets" is currently only a framework, and specific recommendations will be developed in future versions.
Table 1: Draft Disclosure Recommendations for the TISFD Framework
governance | strategy | Impact and Risk Management | Indicators and targets* |
Disclose corporate governance regarding human-related impacts, dependencies, risks, and opportunities (IDROs). | Disclose the interaction between the people-related IDRO and the organization's business model and strategy, as well as the related financial impact. | Disclose the processes the organization uses to identify, evaluate, prioritize, and monitor people-related IDROs. | Disclose the indicators and targets used to evaluate and manage human-related IDROs. |
A. Explanation of the supervisory system for IDROs related to human resources. | A. The organization has identified a person-related IDRO. | A. This document describes the process for identifying, evaluating, and prioritizing people-related IDROs (Individual Disability Resources) across our business activity and the upstream and downstream of our value chain. | A. Disclose the metrics that organizations use to evaluate and manage people-related impacts and dependencies. |
B. This section describes the role of management in the governance processes, controls, and procedures used to monitor, manage, and oversee IDROs related to people. | B. This explains the interrelationship between people-related IDROs, the organization's business model and strategy, and related financial impacts. | B. This document describes the organizational process for monitoring IDROs related to people. | B. Disclose the metrics that companies use to assess and manage people-related risks and opportunities. |
C. This document explains stakeholder engagement approaches for IDROs related to people, and how the perspectives of affected stakeholders are incorporated into governance and management decision-making. | C. This section describes the resilience of an organization's strategy and business model to people-related risks and opportunities. | C. This section explains how the process of identifying, assessing, prioritizing, and monitoring people-related risks is integrated into the organization's overall risk management process. | C. This section describes the goals and metrics used by the organization to manage human-related IDROs, as well as their performance. |
* The disclosure recommendations regarding "metrics and targets" are planned to be included in the next beta version of the framework.
Zeroboard Create based on TISFD Framework (Beta Version 0.1) *1)
The general requirements apply across the board to five areas: materiality, system-related information, stakeholder engagement, scope (the scope and expansion plan for assessment and disclosure), and time axis (definitions and considerations of short, medium, and long term). Regarding materiality, as mentioned earlier, taking into account IDRO's considerations, the design is intended to accommodate financial materiality, impact materiality, and double materiality, and is based on the choice of the disclosing organization. Alignment with international standards for responsible corporate conduct, such as the UN Global Compact and the OECD Guidelines for the Conduct of Multinational Enterprises, is also explicitly stated.
How should Japanese companies deal with TISFD?
While there is currently no legal obligation to disclose information under the TISFD framework, the disclosure of human capital in securities reports will be expanded from the fiscal year ending March 2026 (*8) , and existing standards such as IFRS S/SSBJ, GRI, and CSRD/ESRS also require the disclosure of social information. Therefore, institutional investors are likely to demand that their investees disclose information in accordance with TISFD, and it is highly probable that this will be incorporated into disclosure requirements in the future. Effective preparation for Japanese companies would be to first proceed with conducting human rights due diligence in accordance with international standards and to reorganize their efforts regarding human capital and human rights in their supply chains within the framework of IDRO.
Version 0.1 outlined a disclosure framework, but the indicators were not yet developed, and the disclosure approach to system-level risks remains in the realm of generalities. Whether to establish indicators related to inequality such as living wages, to present a menu of indicators that take regional differences into account, or to utilize existing indicators from GRI and ESRS are Issue to be discussed in the future *9) . For Japanese companies, expanding the disclosure processes cultivated under TCFD and TNFD and establishing a data infrastructure that spans climate, nature, and society will be the quickest way to prepare for future demands. For Japanese companies, which have been criticized for lagging behind in the social (S) aspect of ESG, TISFD also presents an opportunity to re-examine structural Issue such as human rights and inequality from a financial and strategic context *10) .
Key points of public comments and participation in the pilot program
Public comments are accepted until July 31, 2026. Comments can be submitted by registering for a free account on the TISFD official website (tisfd.org) and directly inserting comments into the relevant sections of the framework text.
The report seeks written feedback (in English only) on general requirements, disclosure recommendations, interoperability with existing disclosure standards, and relevance to climate and nature *11) . Insights from a wide range of stakeholders, not just companies and investors, are needed regarding the clarity of concepts and definitions, practical usability, and suitability to disclosure needs. In particular, opinions that take into account Japan's Industry structure, employment practices, and supply chain realities would be useful regarding the concept of materiality, specific disclosure methods for system-related information, guidance on impact and dependency assessment, and prioritization of indicators and targets.
TISFD is attempting to define a third disclosure, "people," following climate change and natural capital, but version 0.1, as its name suggests, is still in the testing phase of the reporting architecture. Japanese companies are encouraged to understand the concept of IDRO now and proactively participate in the framework's formation, keeping in mind its connection to existing human capital and sustainability disclosures. In addition to public comments, expressing interest in the upcoming pilot tests would also be beneficial. Our company is also participating in the "TISFD Alliance" and following the discussions, and we will continue to keep you updated on future developments.
*1) Taskforce on Inequality and Social-related Financial Disclosure (TISFD), The TISFD Framework: Recommendations on disclosure of people-related information by businesses and financial institutions, Beta Version 0.1, 26 May 2026. https://www.tisfd.org/frameworks/tisfd-framework-beta-version-0-1
*2) Taylor Wessing, “Completing the jigsaw: the launch of the Taskforce on Inequality and Social-related Financial Disclosures”, 11 December 2024. https://www.taylorwessing.com/en/insights-and-events/insights/2024/12/completing-the-taskforce-jigsaw
*3) TISFD, People in Scope: An overview of the proposed scope, approach, governance structure, and work plan of the Taskforce on Inequality and Social-related Financial Disclosures, September 2024. https://www.tisfd.org/downloads
*4) TISFD, Steering Committee. https://www.tisfd.org/about/steering-committee
*5) TISFD, Proposed Technical Scope: Recommendations for the TISFD from its Founding Partners, March 2025. https://www.tisfd.org/downloads
*6) TISFD, Conceptual Foundations: Understanding relationships between business, finance, people and inequality, A discussion paper, October 2025. https://www.tisfd.org/downloads
*7) London Reporting Academy, “TISFD sets out a draft for social reporting”, 28 May 2026. https://reporting.academy/en/pages/tisfd-sets-out-a-draft-for-social-reporting
*8) Yukari Yasuhara, "Expansion of Human Capital Disclosure in Annual Securities Reports: Key Disclosure Points Required by the Revision," Nikkei BP Human Capital Online, May 28, 2026 https://project.nikkeibp.co.jp/HumanCapital/atcl/column/00008/052600072
*9) Kaori Fujita, "'Inequality among people is a financial risk' - Executive Director of TISFD, Human Capital and Human Rights Information Disclosure Standards," Nikkei Business, January 9, 2026 https://business.nikkei.com/atcl/gen/19/00159/122600362
*10) Naka, Mio. "The Concept of the Task Force on Inequality and Socially Related Financial Disclosures (TISFD) and its Implications for Japanese Companies: How to Understand and Address Impacts, Dependencies, Risks and Opportunities (IDROs)," Daiwa Institute of Research ESG Investment, July 2025. https://www.dir.co.jp/report/research/capital-mkt/esg/20250714_025202.pdf
*11) TISFD, Provide Feedback. https://framework.tisfd.org/provide-feedback
Related articles
-
Deciphering the Exposure Draft of the EU Disclosure Standard "ESRS-40a" for Non-EU Companies - Limitations on Impact and Value Chain Voluntary Standards (Public Comment Period Ends October 31)
-
Public comments on the revised GHG protocol Scope 2 have been released — Multiple methods to be considered due to disagreements over hourly matching, etc.
-
Measurement and Disclosure for Nature Positive "Implementation" - The Kumamoto Summit Showcased the Two Pillars of Impact and "Dependence"
-
What is Supply Chain Security? An explanation of implementation design and SCS evaluation systems to prevent procurement disruption risks.
Ongoing Webinars
-
[Recorded Broadcast] This is not someone else's problem—Why supply chains are becoming a management Issue: An interview with Kenji Fuma on how companies could have prepared and acted.
Location: Online (Zoom)Participation fee: Free -
This is not someone else's problem—Why supply chains are becoming a management Issue: An interview with Kenji Fuma on how companies could have prepared and acted.
Location: Online (Zoom)Participation fee: Free -
[Sponsored by Keidanren] What can AI do to make society sustainable?
~ Zeroboard's 5th Anniversary Conference "The Zeroboard Day 2026"~Location: Online (Zoom) *Archive streaming will be available at a later date.Participation fee: Free -
[Sponsored by Keidanren] The Essence of Sustainability Management Supported by the Front Lines: The Zeroboard 5th Anniversary Conference "The Zeroboard Day 2026"
Location: Online (Zoom) *Archive streaming will be available at a later date.Participation fee: Free
-
Deciphering the Exposure Draft of ESRS-40a, the Disclosure Standard for Non-EU Companies: Limitations on Impact and Value Chain Voluntary Standards (Public Comment Period Ends October 31)
-
Public comments on the revised GHG protocol Scope 2 have been released — Multiple methods to be considered due to disagreements over hourly matching, etc.
-
Measurement and Disclosure for Nature Positive "Implementation"—The Kumamoto Summit Revealed the Two Pillars of Impact and "Dependence"
-
What is Supply Chain Security? An explanation of implementation design and SCS evaluation systems to prevent procurement disruption risks.
-
Feeling the limitations of managing supplier surveys (CSR surveys) with Excel? How SAQ systemization can solve these problems.